Difference Between GSTR 2A and 2B
Understanding the Difference Between GSTR 2A and 2B is essential for every GST-registered business to claim Input Tax Credit (ITC) accurately and maintain proper GST compliance. Both statements provide details of purchases and inward supplies reported by suppliers, but they differ in their update frequency and how businesses use them to verify eligible ITC.
When analysing the Difference Between GSTR 2A and 2B, businesses may notice variations in the reported figures due to supplier filing timelines and statement updates. Understanding these differences helps businesses reconcile purchase records, identify discrepancies, avoid ITC claim errors, and ensure accurate and hassle-free GST return filing.
What is GSTR-2A?
When understanding the Difference Between GSTR 2A and 2B, GSTR-2A is an auto-drafted statement that displays details of inward supplies reported by a taxpayer’s suppliers through their GST returns. It helps businesses verify purchase invoices and track the Input Tax Credit (ITC) reported by suppliers.
One key feature of GSTR-2A is that it is dynamic, meaning the information can change whenever suppliers upload, modify, or file relevant invoice details.
For example, if a supplier uploads an invoice after you have checked GSTR-2A, the invoice may appear later. Similarly, any amendments made by the supplier can update the details reflected in the statement.
Understanding the Difference Between GSTR 2A and 2B helps businesses recognise how GSTR-2A supports supplier filing tracking, identification of missing invoices, and purchase reconciliation for accurate GST compliance.
What is GSTR-2B?
Understanding the Difference Between GSTR 2A and 2B helps businesses recognise the role of GSTR-2B in claiming Input Tax Credit (ITC). GSTR-2B is an auto-drafted ITC statement generated for registered taxpayers. It provides details of eligible and ineligible ITC based on information furnished by suppliers and other relevant sources.
Unlike GSTR-2A, GSTR-2B is a static statement, meaning the details remain fixed for the relevant tax period once generated. For monthly taxpayers, GSTR-2B is generally made available on the 14th day of the following month.
Knowing the Difference Between GSTR 2A and 2B helps businesses identify eligible ITC, reconcile purchase invoices, and verify credit details before filing GSTR-3B. This process supports accurate ITC claims and ensures better GST compliance.
GSTR-2A vs GSTR-2B: What is the Difference?
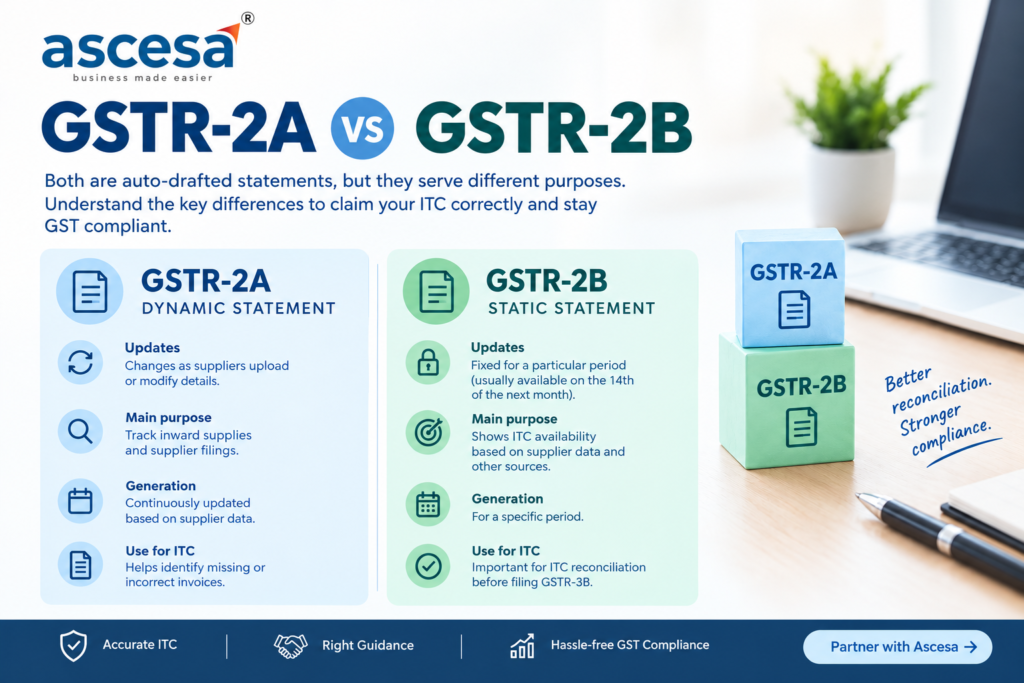
The main difference between GSTR-2A vs GSTR-2B is their nature and purpose.
| Particulars | GSTR-2A | GSTR-2B |
|---|---|---|
| Nature | Dynamic statement | Static statement |
| Main purpose | Track inward supplies | Determine ITC availability |
| Updates | Can change when supplier data changes | Provides a fixed statement for the relevant period |
| ITC reconciliation | Useful for tracking supplier invoices | Important for ITC reconciliation |
| Generation | Continuously updated based on supplier filings | Generated for a specific period |
| Use with GSTR-3B | Supporting reference | Important reference for ITC reporting |
The key aspect of the Difference Between GSTR 2A and 2B is that GSTR-2A is primarily used to monitor supplier-reported transactions, whereas GSTR-2B provides a structured statement to assess eligible Input Tax Credit (ITC).
The GST Portal also implements system-based checks to compare the ITC available in GSTR-2B with the ITC claimed in GSTR-3B, helping businesses maintain accurate GST records.
Why Can GSTR-2A and GSTR-2B Show Different Amounts?
Understanding the Difference Between GSTR 2A and 2B helps businesses identify discrepancies and maintain accurate Input Tax Credit (ITC) records. The amounts reported in both statements may vary because they follow different reporting and timing mechanisms.
Some common reasons for differences between GSTR-2A and GSTR-2B include:
- Suppliers upload or file invoices after the relevant GSTR-2B cut-off date.
- Suppliers make amendments to previously reported invoices.
- Credit notes and debit notes are reported in different tax periods.
- Suppliers file their GST returns late.
- Certain transactions are reflected according to specific system timelines.
- Import-related information is included in GSTR-2B through the relevant systems.
Understanding the Difference Between GSTR 2A and 2B helps businesses reconcile purchase records, verify eligible Input Tax Credit (ITC), and avoid errors while filing GST returns.
Therefore, businesses should carefully compare GSTR-2A and GSTR-2B before claiming ITC. Not every difference between these statements indicates an error. However, proper reconciliation helps identify missing invoices, verify eligible ITC, and maintain accurate GST records and compliance.
Which Statement Should Businesses Use for ITC?
When understanding the Difference Between GSTR 2A and 2B for Input Tax Credit (ITC) reconciliation, businesses should give particular importance to GSTR-2B before filing their GST returns.
GSTR-2B provides details of ITC availability based on documents reported by suppliers and other relevant sources. It serves as an important reference for verifying eligible ITC before filing GSTR-3B. The GST Portal also uses GSTR-2B-related data to help auto-populate relevant ITC details in GSTR-3B.
However, businesses should not claim every amount shown in GSTR-2B without proper verification. Understanding the Difference Between GSTR 2A and 2B, checking applicable GST conditions, verifying invoice details, and reviewing ITC eligibility requirements can help businesses avoid incorrect claims and maintain proper GST compliance.
How Businesses Can Reconcile GSTR-2A and GSTR-2B
Understanding the Difference Between GSTR 2A and 2B is important for maintaining accurate purchase records and claiming the correct Input Tax Credit (ITC). A proper reconciliation process helps businesses identify missing invoices, incorrect GSTINs, duplicate entries, and supplier filing issues.
A simple reconciliation process includes:
- Download the relevant GSTR-2A and GSTR-2B statements.
- Compare purchase records with the GST statements.
- Identify invoices that are missing or mismatched.
- Check supplier filing status and invoice details.
- Review eligible and ineligible ITC separately.
- Follow up with suppliers wherever corrections are required.
- Reconcile the final figures before filing GSTR-3B.
Regular reconciliation of GSTR-2A and GSTR-2B helps businesses understand ITC differences, minimise errors, and maintain smooth GST compliance. is better than waiting until the end of the financial year because errors can become more difficult to trace later.
Common Mistakes Businesses Should Avoid
Understanding the Difference Between GSTR 2A and 2B helps businesses avoid common mistakes while claiming Input Tax Credit (ITC) and maintaining GST compliance. Businesses should not treat both statements as interchangeable, as each serves a different purpose in ITC reconciliation.
Common mistakes to avoid include:
- Claiming ITC without verifying its eligibility.
- Ignoring differences between purchase records and GST statements.
- Not following up with suppliers regarding missing invoices.
- Assuming that an invoice appearing in a statement automatically makes the ITC eligible.
- Failing to reconcile ITC before filing GSTR-3B.
- Depending only on GSTR-2A for final ITC calculations.
Understanding the Difference Between GSTR 2A and 2B and following a consistent reconciliation process can help businesses maintain accurate GST records, minimise ITC-related errors, and ensure better GST compliance.
Frequently Asked Questions
1. What is the main Difference Between GSTR 2A and 2B?
The main difference between GSTR 2A and 2B is that GSTR-2A is a dynamic statement that changes whenever suppliers update their filings, whereas GSTR-2B is a static statement generated for a specific tax period.
2. Is GSTR-2B important for claiming ITC?
Yes. GSTR-2B is an important reference for reviewing Input Tax Credit (ITC) available for a particular tax period. However, taxpayers must also verify whether the ITC satisfies all applicable GST conditions before claiming it.
3. Why is my GSTR-2A higher than GSTR-2B?
GSTR-2A may be higher than GSTR-2B because it is a dynamic statement that reflects supplier updates and amendments over time. Some invoices or amendments may fall outside the relevant period or cut-off used for generating GSTR-2B. These differences should be properly reconciled rather than automatically treated as errors.
4. Should businesses reconcile GSTR-2A and GSTR-2B?
Yes. Understanding the Difference Between GSTR 2A and 2B helps businesses identify missing invoices, mismatches, duplicate entries, supplier filing issues, and potential ITC differences. Regular reconciliation provides better visibility into purchase transactions and ITC claims.
5. Can I claim all ITC shown in GSTR-2B?
Not necessarily. The appearance of an amount in GSTR-2B does not automatically make it eligible for an ITC claim. Businesses should verify applicable GST conditions, check invoice details, and reconcile the figures with their purchase records and other GST documents before claiming ITC.
Conclusion
Understanding the Difference Between GSTR 2A and 2B is essential for accurate GST compliance and effective Input Tax Credit (ITC) management. While GSTR-2A provides a dynamic view of supplier-reported inward supplies, GSTR-2B offers a static, period-wise statement that plays an important role in ITC reconciliation.
Businesses should regularly reconcile GSTR-2A and GSTR-2B by comparing purchase records with both statements, identifying mismatches, following up with suppliers for corrections, and verifying ITC eligibility before filing GSTR-3B.
Understanding the Difference Between GSTR 2A and 2B and following proper reconciliation practices can help businesses minimise ITC errors, maintain accurate GST records, and avoid unnecessary compliance issues.
If your business needs professional assistance with GST reconciliation, ITC verification, or GST return filing, Ascesa Business Services can help you manage your GST compliance efficiently and accurately. compliance more effectively.